How to Cash Out Crypto to a Bank Account: Statistics and Costs for 2026
Cashing out crypto sounds complicated, but the basic path is short. You sell the crypto for local currency on a regulated exchange. Then you withdraw the cash balance to your bank account.
The numbers behind that path vary a lot. Listed withdrawal times range from about 30 minutes to three business days. On a $10,000 sale, direct costs can run from $28 to $230, depending on the method.
This article looks at the main figures for 2026. It covers timing, fees, limits, taxes and common mistakes. The data comes from published guidance by Coinbase, Binance and Crypto.com.
How Cashing Out Crypto Works
Your bank receives fiat money, not Bitcoin or Ethereum. Crypto does not move directly into a traditional bank account. A bank account has no Bitcoin blockchain address, so something has to convert the coins first.
That something is most often a crypto exchange. Platforms such as Coinbase, Kraken, Binance and Crypto.com sell the crypto for euros, dollars or pounds. They then send the cash through a normal payment system.
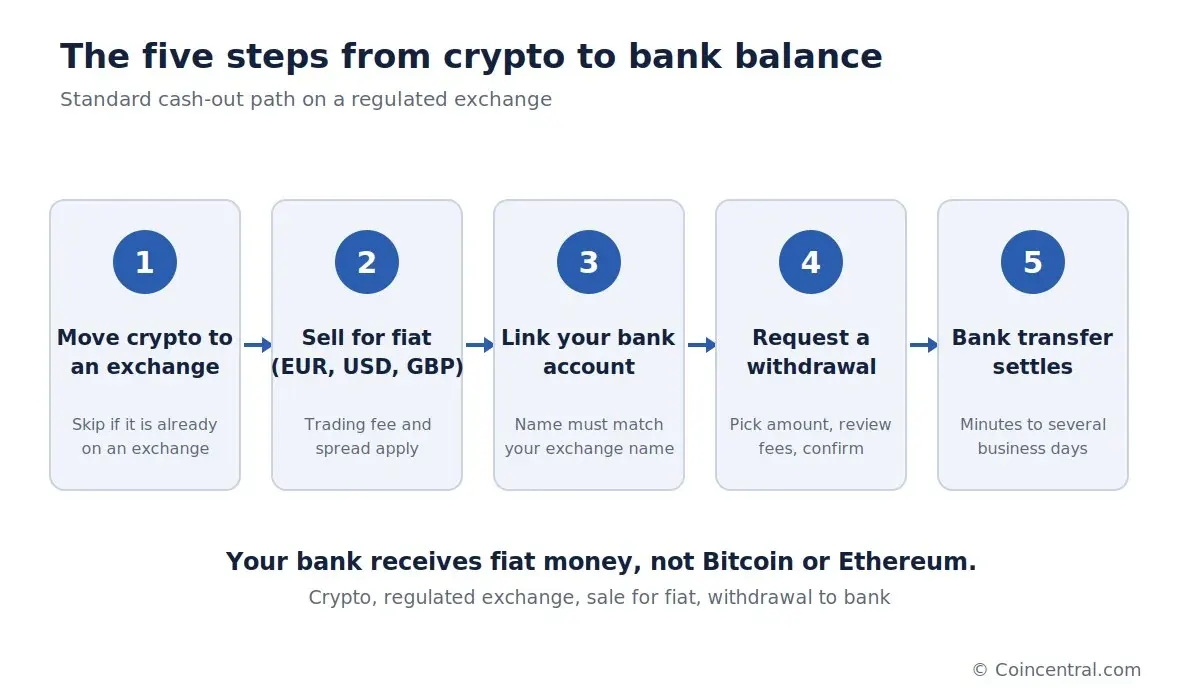
The standard process has five steps. If your crypto is already on an exchange that supports bank withdrawals, the first step is not needed. Coinbase, for example, requires users to sell crypto into a cash balance before they can withdraw it.
| Step | What happens | Detail |
|---|---|---|
| 1. Transfer | Send crypto from a self-custody wallet to the exchange | Skip if already on the exchange |
| 2. Sell | Convert the crypto into EUR, USD, GBP or another fiat currency | Trading fees and spread apply |
| 3. Link bank | Verify the bank account | Name must match the exchange account |
| 4. Withdraw | Choose the account, enter the amount, review fees | Confirm the transfer |
| 5. Settle | The bank transfer arrives | Minutes to several business days |
The first step carries its own risk. You must choose the correct network when you send coins. If you send an asset over a network the exchange does not support, it may not be credited, and the money could be hard or impossible to recover.
A small test transaction is often a smart move for large amounts. On a $100,000 cash out, a test send can confirm that the address, the network and the exchange all work. The extra network fee is small next to the cost of a mistake.
Stablecoins follow the same path. A holder deposits USDC on an exchange, converts it to USD or EUR, and withdraws the cash. Stablecoins carry issuer, depegging, blockchain and wallet risks, so they should not be treated as bank deposits.
Some fintech services combine the steps in one screen, which can feel like a direct Bitcoin withdrawal. Behind the scenes, the crypto is still sold first.
How Long Does a Crypto Withdrawal Take?
Withdrawal times depend on the exchange, the payment network and the country. The full process can take anywhere from minutes to several business days. The listed figures below come from each platform’s own guidance.
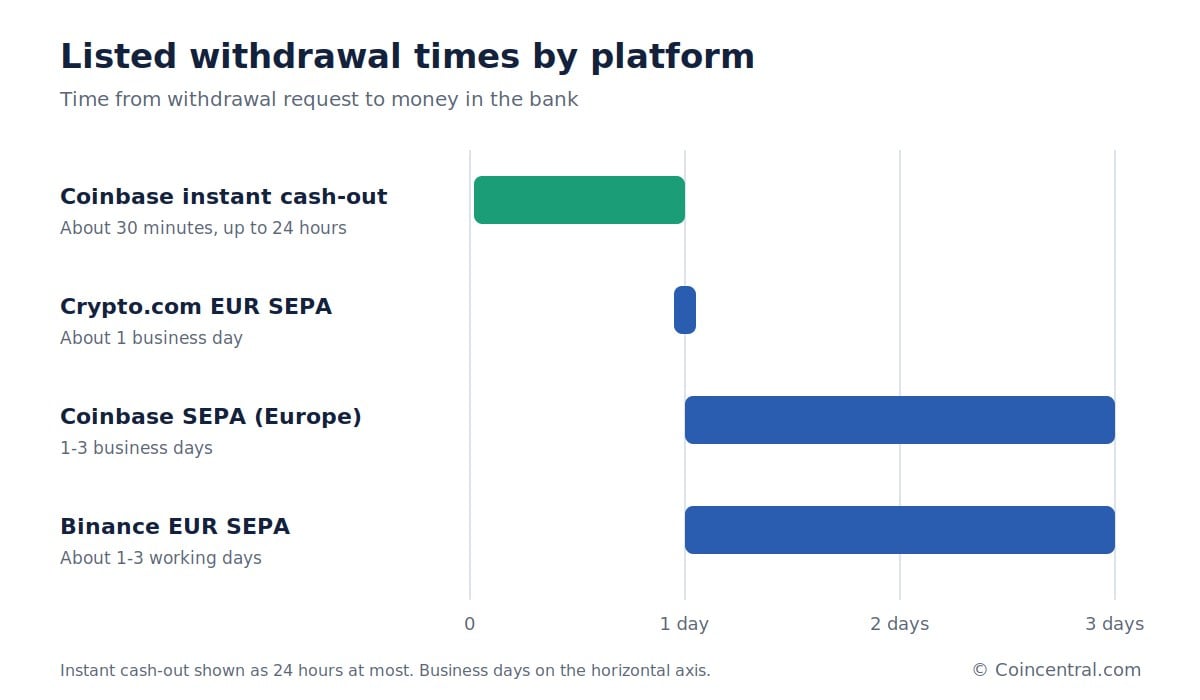
For European Coinbase customers, standard SEPA settlement is listed at 1-3 business days. Eligible instant cash-outs typically arrive in around 30 minutes. Coinbase says they can take up to 24 hours, depending on the bank or card provider.
Binance lists about 1-3 working days for transfers in its EUR SEPA verification process. Crypto.com lists about one business day for EUR SEPA withdrawals through its European service.
| Platform | Method | Listed time |
|---|---|---|
| Coinbase | SEPA (Europe) | 1-3 business days |
| Coinbase | Instant cash-out (eligible users) | About 30 minutes, up to 24 hours |
| Binance | EUR SEPA | About 1-3 working days |
| Crypto.com | EUR SEPA | About 1 business day |
SEPA stands for Single Euro Payments Area. It allows euro transfers between participating banks across Europe. A typical European route is BTC, sell for EUR, EUR balance, SEPA transfer, bank account.
Other regions use other systems. Depending on the country, the payout may travel by ACH, Faster Payments, SWIFT, Real Time Payments or a card cash-out service. Once the exchange has converted the crypto into fiat, this last stage is a normal financial transfer.
International SWIFT transfers can take longer. Weekends, public holidays, bank compliance checks and intermediary banks can add more delay. Availability also differs by country, so the withdrawal screen in your own account is the best guide.
What Does It Cost to Cash Out Crypto?
There is no single fee. The total comes from several parts, and each one depends on the platform and the method. Some parts may not apply to you at all.
| Cost | What it is | Example from the sources |
|---|---|---|
| Blockchain fee | Network fee to move self-custody crypto to an exchange | Depends on congestion and transaction size. On Ethereum it is called gas |
| Trading fee | Charge for selling the crypto | 0.25% on a $50,000 sale is $125 |
| Spread | Gap between the market price and the price you get | Market price $80,000, sale at $79,600, a $400 gap |
| Withdrawal fee | Fixed or percentage charge to take out cash | Crypto.com lists no fee for eligible EUR SEPA withdrawals |
| Bank or intermediary fees | Charges from other banks on international transfers | Binance warns SWIFT transfers can arrive with less than expected |
| Currency conversion | Cost of switching between currencies | Can apply if the bank account uses a different currency |
Where you sell matters. An advanced trading interface is often cheaper than an instant Sell button. A professional order-book screen may charge a fraction of one percent.
A simplified retail screen may charge more and build a spread into the quoted price. On the $80,000 example above, a $400 gap equals 0.5% of the sale. That cost never appears as a separate line, which is why the execution price is worth checking.
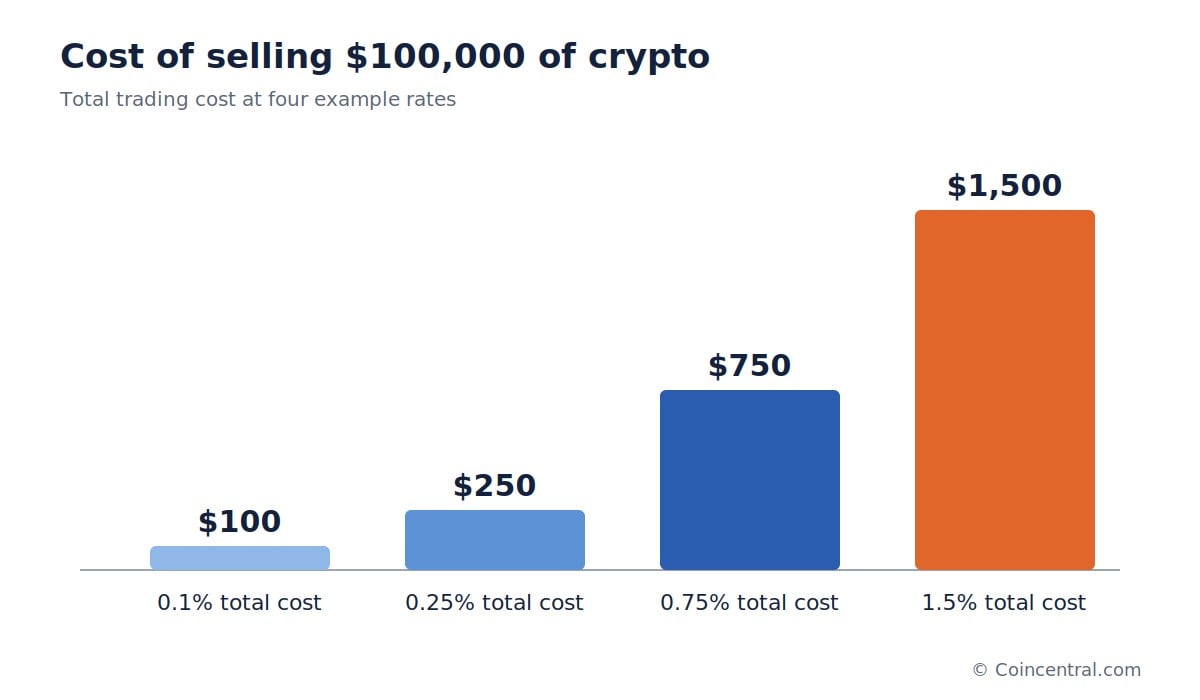
The gap grows with the amount. On a $100,000 sale, a total cost of 0.1% is about $100. At 1.5%, the cost is $1,500.
| Total cost rate | Cost on a $100,000 sale |
|---|---|
| 0.1% | $100 |
| 0.25% | $250 |
| 0.75% | $750 |
| 1.5% | $1,500 |
Withdrawal fees vary. Some exchanges charge a fixed or percentage fee, and others charge nothing for certain methods. Crypto.com says neither it nor its European EMI partners charge a fee for eligible EUR SEPA withdrawals.
Currency choice adds cost too. If your bank account is in euros and you withdraw dollars, an exchange or bank may convert the money. Binance warns that intermediary banks may convert currency on their own, and that extra charges can reduce the final amount.
For European users, selling straight into EUR and withdrawing through SEPA is often cleaner than routing the money through dollars.
Cost Example: Cashing Out $10,000 of Bitcoin
Suppose you hold $10,000 of Bitcoin in a hardware wallet. You send it to an exchange, sell it and withdraw the cash to your bank. Here are two routes with different fee levels.
On the low-cost route, the network fee is $2. The trading fee is 0.25%, or $25, and the bank withdrawal fee is $1. The total direct cost is $28, and you receive about $9,972.
On the high-cost route, the platform charges a 1.5% transaction fee, which is $150. It also applies a 0.75% effective spread, which is $75, plus a $5 withdrawal charge. The total is $230, and you receive about $9,770.
| Cost item | Low-cost route | High-cost route |
|---|---|---|
| Network fee | $2 | $0 |
| Trading or transaction fee | $25 (0.25%) | $150 (1.5%) |
| Spread | $0 | $75 (0.75%) |
| Withdrawal fee | $1 | $5 |
| Total direct cost | $28 | $230 |
| Cost as a share of $10,000 | 0.28% | 2.3% |
| Amount received | About $9,972 | About $9,770 |
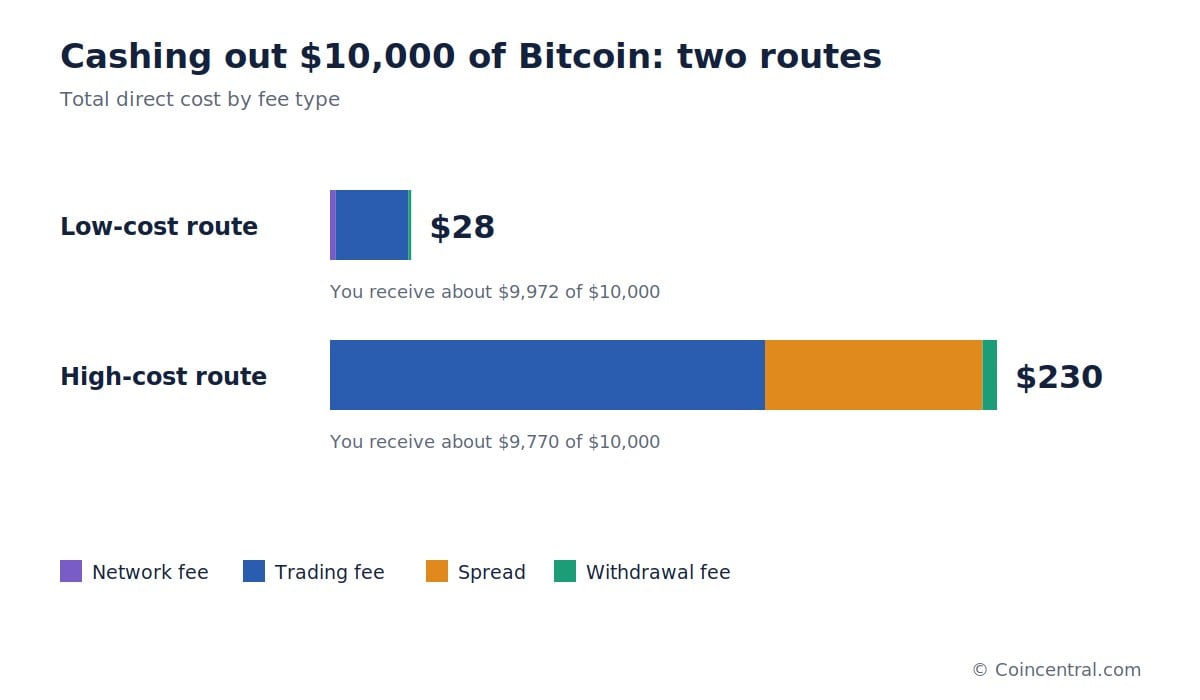
The high-cost route costs more than eight times as much as the low-cost route. The difference is $202 on a $10,000 sale. The same gap in percentage terms would grow with larger sums.
The method used to cash out therefore matters almost as much as the bank withdrawal itself. The sources suggest comparing the actual execution price and fees before selling, rather than focusing only on convenience.
Withdrawal Limits, Verification and Compliance Checks
Withdrawal limits vary by platform and verification level. They can change, and they may be specific to your account. It helps to check them before you sell.
| Platform | Limit | Amount |
|---|---|---|
| Crypto.com (Europe) | Minimum EUR withdrawal | €80 |
| Crypto.com (Europe) | Daily maximum | €100,000 |
| Crypto.com (Europe) | Monthly maximum | €500,000 |
| Coinbase (U.S., instant bank cash-out) | Per-transaction limit | $100,000 |
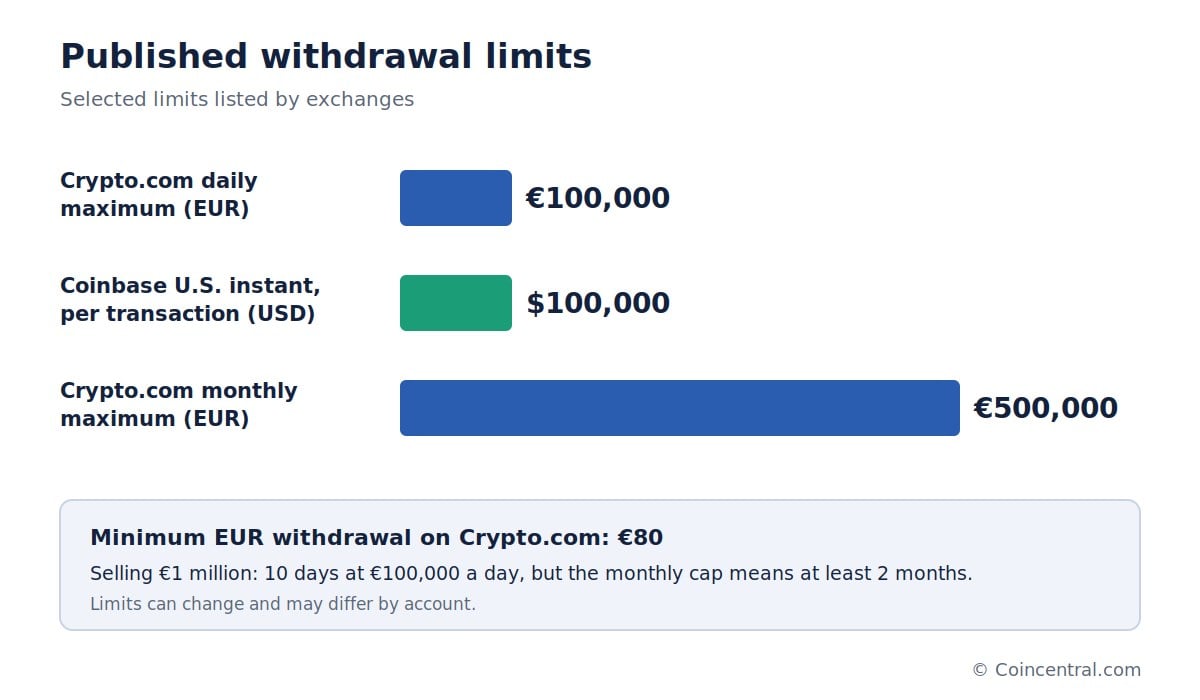
Limits can slow a large cash out. At €100,000 a day, moving €1 million would take 10 days of withdrawals. The €500,000 monthly cap on that service means it would take at least two months.
You do not want to learn this after converting $1 million into cash. Coinbase notes that other bank-transfer methods and account limits can differ from the instant figure.
Account checks also come first. Binance says bank withdrawals must go to an account that matches the name on the Binance account, and it does not support third-party bank withdrawals. Binance and Crypto.com both ask European users to make an initial SEPA deposit from the bank account they want to verify.
Large transfers can trigger routine reviews. Exchanges and banks work under anti-money-laundering rules. A seven-figure transfer is more likely to get attention than a €500 one.
An exchange may ask for source-of-funds or source-of-wealth information. It may also ask for transaction history or proof that you own the wallet. A bank could ask where a €100,000 transfer came from, and exchange statements make a stronger answer than the word Bitcoin.
A bank can temporarily hold or review incoming money that triggers fraud, sanctions or anti-money-laundering controls. That does not mean the money has been taken. The bank may simply ask for documents that show where it came from.
Splitting one legitimate large transfer into many small ones to avoid scrutiny can create more compliance concerns, not fewer. Useful records include exchange purchase history, bank statements showing the original deposits, wallet transaction records, tax returns and proof of earlier crypto purchases.
Cash Out Strategies and Other Ways to Sell
Cashing out does not have to mean selling everything. Someone holding 5 BTC might sell 0.25 BTC to cover living costs and keep the rest invested.
Others sell in stages. They might sell 10% at one price level, another 10% after a further rally, and keep the remainder as a long-term holding. This can reduce the risk of trying to pick the exact top of the market.
Take an investor with $200,000 in crypto who sells $20,000 a month for ten months. The chart below shows the cash received at each step.
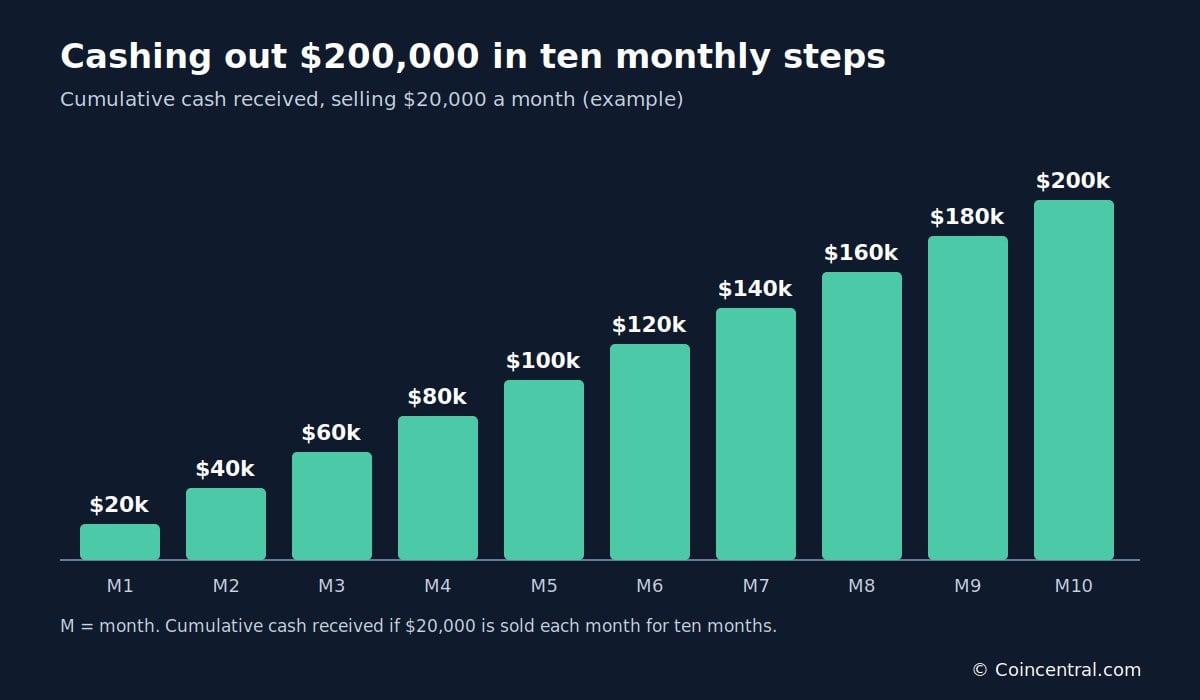
Staging has a trade-off. The market could fall before the remaining assets are sold. The source article says there is no mathematically guaranteed best approach, and that the key is to set a plan before emotions take over.
If you need the money right away, one sale may make more sense. Tax outcomes can also differ between one sale and several, depending on the country.
Exchanges are not the only route. The table below compares the main options.
| Method | Best suited to | Main risks |
|---|---|---|
| Regulated exchange | Most retail users | Fees, spreads and withdrawal limits |
| Peer-to-peer sale | Selling directly to another person | Fraud, fake bank transfers, chargebacks, stolen bank accounts, disputes |
| Crypto ATM | Selling Bitcoin for cash | Fees can be substantially higher than online exchanges |
| OTC desk | Very large trades by funds, companies and wealthy investors | Identity checks and a quote process |
An over-the-counter desk can find a buyer directly and agree on a price. This avoids placing one huge order on a public exchange, which could move the market against the seller. Bitcoin is liquid enough that ordinary retail trades rarely need this.
Established peer-to-peer platforms may offer escrow, but users still need to understand the risks.
Taxes Can Be the Biggest Cash-Out Cost
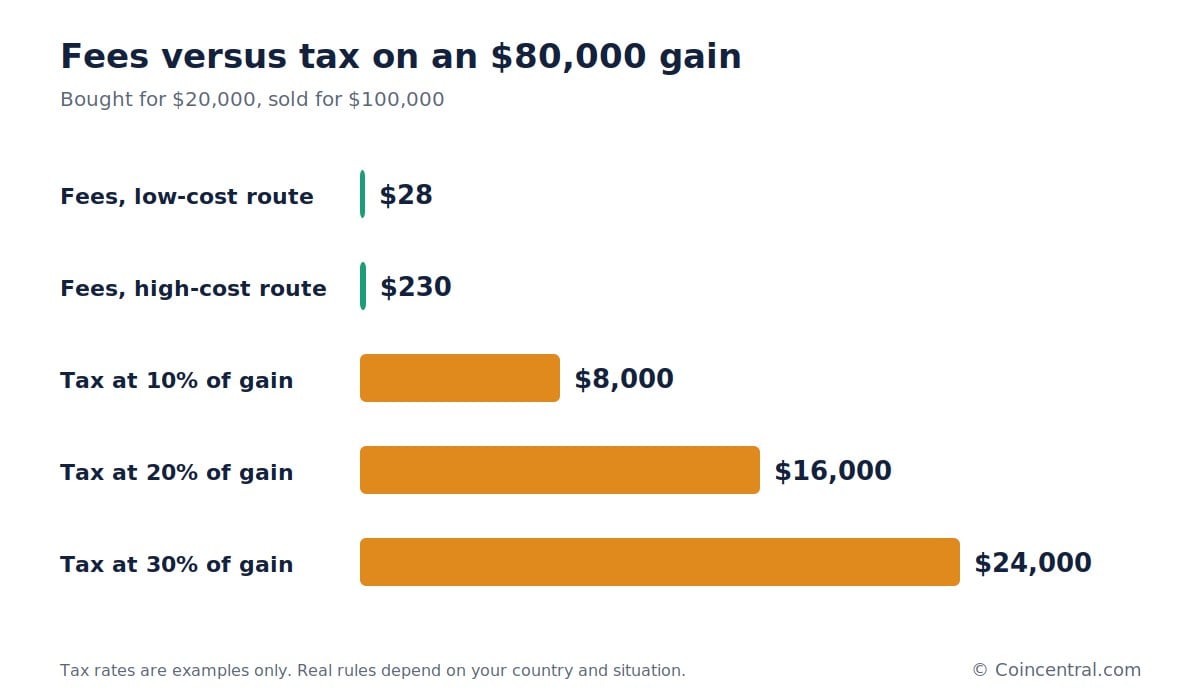
Trading and banking fees can be small next to tax. Suppose you bought Bitcoin for $20,000 and sold it for $100,000. Your gain is about $80,000 before allowable costs.
Depending on your country, some or all of that gain may be taxable. The taxable event is often the sale of the crypto, not the moment the money reaches your bank. Leaving the proceeds on an exchange does not necessarily postpone the tax.
Rules differ widely. Some places tax crypto gains as capital gains. Others use different classes based on holding period, trading frequency, professional status or the type of activity.
The table uses example rates only, to show scale. It is not tax advice, and real rules depend on where you are tax resident.
| Example tax rate | Tax on an $80,000 gain | Compared with $230 in fees |
|---|---|---|
| 10% | $8,000 | About 35 times |
| 20% | $16,000 | About 70 times |
| 30% | $24,000 | About 104 times |
Good records make tax reporting easier. Keep the purchase date, purchase price, amount bought and fees. Also keep the sale date, sale proceeds, the exchange used and any wallet transfers.
If coins moved through several wallets, save the transaction hashes. Moving your own Bitcoin from Wallet A to Wallet B is not the same as selling it. Records help show which events were transfers and which were sales.
This matters when an exchange’s tax software sees crypto arriving from an unknown outside wallet. Without the original purchase price, it cannot work out the gain.
Common Mistakes and Safety Steps
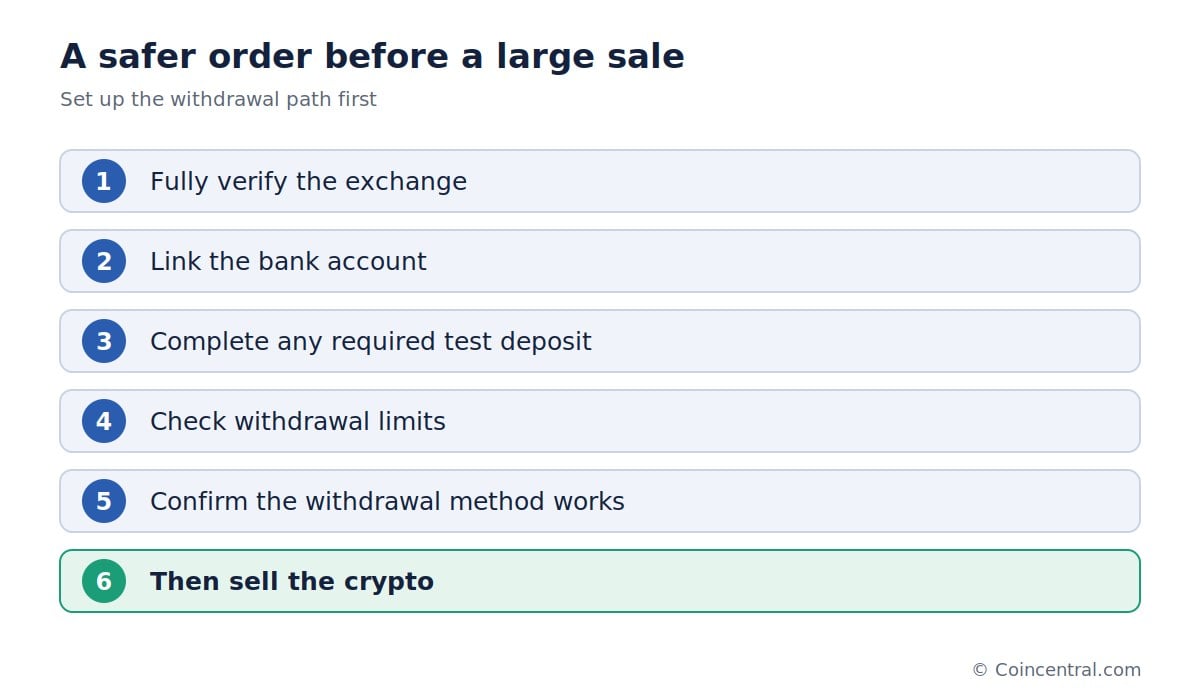
One common mistake is selling before the bank withdrawal is ready. Imagine you hold €100,000 of Bitcoin and sell it. Then you find your bank account is not verified and withdrawals are paused.
That €100,000 now sits in the exchange cash balance while you wait. A better order is to set up the withdrawal path first, as the chart shows.
A second mistake is using the wrong currency. A euro account that receives a dollar withdrawal may face conversion costs from the exchange, the intermediary bank or the receiving bank.
Most safety risks are practical. They include sending crypto to the wrong address, using the wrong blockchain, falling for phishing, entering wrong bank details, using an unregulated platform and ignoring tax duties.
| Risk | Precaution |
|---|---|
| Account takeover | Strong unique password and two-factor authentication |
| Wrong withdrawal address | Withdrawal-address whitelisting |
| Phishing | Anti-phishing codes where available |
| Wrong bank details | Verified bank details and a small test transfer |
| Fake support staff | Never share your seed phrase or private key |
Security matters most during large withdrawals. A criminal who reaches an exchange account just before a big cash out can cause heavy losses.
The Bottom Line
The path from crypto to a bank account is simple: crypto, regulated exchange, sale for fiat, withdrawal to bank. If the crypto is already on an exchange, the transfer step can be skipped.
Listed times run from about 30 minutes for eligible instant cash-outs to 1-3 business days for SEPA. Costs on a $10,000 sale ranged from $28 to $230 in the source example, which shows how much the method matters.
As the amount grows, preparation matters more. For a €500 withdrawal, little planning is needed. For €500,000, it helps to know the fees, limits, source-of-funds checks and tax rules before you press Sell.
Sources
- Coinbase: Cash Out Available Balance. Current process for selling crypto into a cash balance and withdrawing to a bank or supported payment method.
- Coinbase: Instant Cashouts. Current instant bank and card cash-out options, expected settlement times and limits.
- Coinbase: Payment Methods for Europe. SEPA and other EU cash-out methods, including standard settlement times.
- Binance: Fiat Withdrawals via Bank Transfer. Bank-transfer withdrawal process, account-name requirements and information on possible intermediary-bank charges.
- Binance: EUR Withdrawals via SEPA. European SEPA withdrawal and bank-verification process.
- Binance: Instant Bank Transfer. Account verification, settlement and eligibility requirements for supported instant transfers.
- Crypto.com: EUR Fiat Deposits and Withdrawals via SEPA. European withdrawal process, fees, processing time and limits.
This story was originally published by Blockonomi. Read the original article.